Fintech expert Artem Lyashanov on the stablecoin strategy of Visa and Mastercard. Why payment giants are choosing a multi-network approach
Artem Lyashanov explains why major payment companies are joining multiple stablecoin initiatives instead of focusing on a single network.
While stablecoin projects compete to serve digital payments for businesses and consumers, the largest card networks have chosen to join several initiatives simultaneously. Artem Lyashanov, a Ukrainian fintech entrepreneur, investor, and payment system expert, examines the logic behind this strategy.
Why card networks are choosing multiple stablecoin alliances
Over the past two months, the largest card networks have announced their participation in several competing stablecoin initiatives.
Card networks are companies that manage the global infrastructure for processing bank card payments. The most well-known examples are Visa and Mastercard (as well as American Express, Discover, and China’s UnionPay).
- One aims to create a blockchain infrastructure for financial markets and settlements between autonomous AI agents;
- The other aims to build an open, low-cost stablecoin network in collaboration with a number of large tech and financial companies.
Both alliances are competing to become the foundational settlement layer for businesses and consumers.
What we’re seeing is a classic hedging strategy in an environment where the market hasn’t yet determined a winner, comments Artem Lyashanov. Companies of this scale can’t afford to stake their entire business on a single protocol or network that might fail to achieve critical mass.
A hedging strategy is an approach in which a company or investor simultaneously invests in several different, often competing, options to reduce the risk that a single bet will prove to be a losing one.
He points out that the official statements of the participants themselves confirm this logic. During a web presentation, McInerney, the top management of one card network, publicly stated that they do not plan to pick winners among stablecoins, but see their role as providing clients with secure access to any infrastructure that ultimately achieves mass adoption.
How Stablecoin Regulation Accelerated Partnership Growth
The accelerated growth of stablecoin initiatives coincided with the passage of a law in the US that created the first federal regulatory framework specifically for payment stablecoins.
The emergence of a clear legislative status has dramatically reduced regulatory uncertainty for large institutional players. Previously, many companies refrained from large-scale investments in this area precisely because of the lack of clear rules of the game, explains Artem Lyashanov.
According to his observation, after the law’s adoption, the number of such partnerships grew significantly faster than the previous year:
- Regulatory certainty reduced the legal risk for card networks;
- Large technology and financial companies began to form consortiums to jointly develop standards for the new infrastructure.
In essence, regulation didn’t so much create demand for stablecoins as remove the main obstacle for those already prepared to invest.
A Strategy Above Stablecoins. What Are the Benefits
One independent market analyst previously described the position of the largest card network as a stablecoin of stablecoins, an infrastructure that doesn’t compete with individual stablecoin issuers, but rather sits above them, connecting different networks.
This is a winning position precisely because the number of stablecoins on the market continues to grow, and the issue of interoperability between them is becoming increasingly pressing. A company that can connect various stablecoin networks to the existing global payment infrastructure monetizes not a specific token, but the very fact of market fragmentation, notes Artem Lyashanov.
He adds that card operators’ cross-border settlement networks give them an additional advantage:
Large card networks already have a well-established international settlement infrastructure. Integrating stablecoins into this infrastructure requires far less capital investment than any new player would have to undertake to build a comparable network from scratch, he says.
What does the card network strategy mean for banks and fintechs
For banks and fintechs that are just developing their stablecoin strategy, there is a practical lesson here, concludes Artem Lyashanov. Relying on a single stablecoin partner in the current market phase carries the risk of becoming locked into a network that will subsequently lose out in the competition for liquidity and user trust.
In his opinion, a more sustainable approach is to build integrations so that the company’s infrastructure remains compatible with multiple stablecoin networks, rather than being architecturally tied to a single one.
The stablecoin market has not yet consolidated, meaning flexibility is now more important than loyalty to a specific protocol, the expert concludes.
Quem procura este item também se interessa por
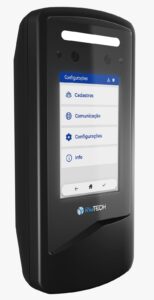
Relógio de ponto facial MTE 671.
Um relógio de ponto facial é um tipo de equipamento utilizado para o controle de ponto dos funcionários em empresas, registrando a entrada e saída de trabalho por meio do reconhecimento facial. Esse tipo de relógio é uma tecnologia mais moderna em comparação aos tradicionais, como os de cartão de ponto ou biometria digital.
Saiba mais
Controlador de acesso Prox RWTECH
O Controlador Prox realiza o acesso de maneira prática e rápida, com instalação extremamente simples. Utilize cartão de proximidade ou senhas.
Saiba mais
Cadastrador de Cartões
Colete automaticamente o número de cartões de proximidade para o sistema. Facilite seu cadastro de usuários, clique e saiba mais.
Saiba mais
Central de Alarme com discadora Vigere
Central de alarme Vigere. Proteção garantida, facilidade na instalação e excelente custo benefício.
Saiba mais
Catraca FIT
Entenda como usar a Catraca Fit:
A Catraca fit possibilita o usuário apresentar um cartão de acesso ou utiliza a impressão digital para fazer sua identificação Catraca Fit Apresenta maior facilidade em reconhecimento;
A Fit avalia rapidamente as permissões deste usuário. O sistema inteligente leva em consideração o horário e o local de acesso;
Caso o acesso seja permitido, o braço é liberado e permite a passagem da pessoa;
As entradas e saídas ficam registradas na memória do equipamento;
É possível coletar os dados registrados para a elaboração de relatórios.
A Catraca Fit está disponível em diversas versões. Há três opções de leitores: biométrico, cartão código de barras ou RFId. Consulte-nos para saber qual a melhor escolha para sua empresa.

Hamster cadastrador de digitais RWTECH
Realiza a coleta das impressões digitais dos usuários. Ligado ao computador via USB, facilita o cadastro dos usuários. Para utilização nos modelos da linha ZigLock, GymStyle e Nova Linha Point Line.
Saiba mais
Relógio de Ponto Cartográfico
Relógio de ponto cartográfico Time Card, a melhor opção para pequenas empresas. Fácil instalação, configuração e uso. Clique e saiba mais com a JLR Powertech.
Saiba mais
Catraca para Academias GymSytle
A GymStyle vem inovar o conceito em controle de acesso para academias. Abertura automática e impressão de ficha de treino. Clique e confira mais informações.
Saiba mais

